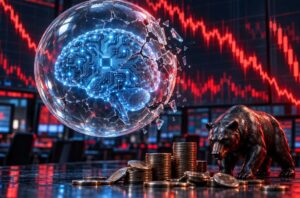
Fears that an investment bubble is forming around artificial intelligence are increasingly worrying investors. If it were to burst, it could trigger a sharp fall in share prices and significantly reduce the value of investments in funds tracking the US S&P 500 stock market index.
According to the scenario outlined in the provided text, an investment of $10,000 in an exchange-traded fund (ETF), such as the Vanguard S&P 500 ETF, could be worth approximately $7,000 by the end of 2027 if the market were to fall by around 30%, according to The Motley Fool.
This illustrates a potential loss based on historical market declines; it is not a reliable forecast. The author points out that a negative scenario is not the only possible outcome and announces an examination of a historically favourable period for stocks, although that part of the analysis is not included in the supplied excerpt.
According to data from First Trust and Bloomberg cited in the text, the average bull market period since 1942 lasted more than four years.
By contrast, the average bear market lasted slightly more than 11 months. The average cumulative loss during these periods was 31.7%.
Historical data therefore suggest that market downturns have generally been shorter than periods of growth, but severe enough to significantly reduce the value of investment portfolios.
Nevertheless, the average duration and magnitude of previous declines do not determine when the next downturn will begin, how long it will last, or what consequences it will have.
Why Is the AI Boom Being Compared to the Dot-Com Bubble?
The market rally driven by the development of artificial intelligence is frequently compared with the boom in internet companies and the subsequent bursting of the dot-com bubble.
The provided text states that the bear market at that time lasted approximately a year and a half, with the S&P 500 index falling by almost 37%.
However, the author points to differences between the market structures of that period and today.
At the end of 1999, before the bubble burst, the index's ten largest holdings included companies from various industries, including Walmart, General Electric, Exxon Mobil, Citigroup and Home Depot.
This composition meant that the largest companies in the index were not concentrated exclusively in the technology sector.
Could the Heavy Weighting of Technology Companies Increase the Risk?
According to the text, technology stocks account for around 40% of the S&P 500 index, while the author associates all ten of its largest holdings with the development of artificial intelligence.
Such concentration could make the index more sensitive to changes in investor sentiment towards AI companies.
If expectations for AI-related earnings were to weaken sharply, a decline in the largest companies could have a significant impact on the entire index. The author therefore considers the possibility that a potential correction could be more severe than the one at the beginning of the dot-com crisis.
This is an assessment of risk, not a claim that such a decline will necessarily occur.
What Do Technology Stock Valuations Tell Us?
In contrast to the concentration risk, the author argues that technology stocks are valued considerably more moderately than during the dot-com boom, according to certain indicators.
Citing Reuters, the text states that the technology sector's valuation at the time reached as much as 48 times expected earnings over the following 12 months.
The current forward price-to-earnings (P/E) ratio is estimated at approximately 19 in the supplied excerpt.
Based on this, the author concludes that greater exposure to technology companies now comes with less stretched valuations than during the internet bubble.
As an additional argument, the author cites data from Yardeni Research, according to which the S&P 500's PEG ratio stands at around 0.7, its lowest level in more than 30 years.
In this context, the PEG ratio represents the relationship between the P/E ratio, based on earnings, and the expected earnings growth rate.
According to the same figures, this is only the fifth time since at least 1995 that the ratio has fallen below one, while its average is approximately 1.3.
The supplied excerpt therefore highlights two opposing factors: the index's heavy concentration in companies associated with artificial intelligence and valuation indicators that, according to the cited data, appear more moderate than during the dot-com bubble.
Neither factor, on its own, provides a reliable answer to the question of how much an investment will be worth at the end of 2027.
 Privreda
 Energetika
 Turizam
 Poljoprivreda
 ICT
 Prehrana